Finance
Top Trends in Wealth Management for 2024

By

Reviewed
By Nora Mike
Wealth management is rapidly evolving as technology advances, market dynamics shift, and client expectations grow more complex. In 2024, several significant trends will shape how wealth management firms operate and how advisors serve their clients. Understanding these trends is crucial for both professionals in the industry and clients seeking better management of their assets.
1. Digital Transformation and Automation
Image by jcomp on Freepik
Technology continues to play a central role in wealth management, and 2024 will see a further shift towards automation and digital solutions. With the rise of robo-advisors and AI-driven platforms, firms are increasingly relying on technology to streamline operations, reduce costs, and offer personalized financial advice.
Key Developments:
- Robo-Advisors: Robo-advisors have evolved from basic portfolio management tools to sophisticated platforms offering personalized advice based on algorithms.
- AI and Machine Learning: Wealth managers now use AI for predictive analysis, identifying trends, and optimizing investment portfolios.
- Automation of Administrative Tasks: AI-powered chatbots and automated processes reduce administrative workloads, allowing wealth managers to focus on high-value tasks.
2. Personalization of Services
Clients are demanding more personalized financial advice tailored to their individual goals and values. In 2024, wealth management firms are moving away from one-size-fits-all approaches and offering bespoke services that cater to specific client needs.
Key Developments:
- Behavioral Finance: Wealth managers are leveraging behavioral finance insights to better understand their clients’ risk tolerance and financial behavior.
- ESG and Impact Investing: Clients are increasingly interested in investments that align with their values, particularly in environmental, social, and governance (ESG) criteria.
- Life-Centered Planning: Advisors are now focusing on helping clients achieve life goals, such as retirement, education funding, or philanthropic interests, rather than merely growing wealth.
3. ESG and Sustainable Investing
Sustainability and responsible investing will be a major trend in 2024, with more clients focusing on ESG factors when making investment decisions. Wealth managers must integrate ESG into their portfolios, not just for ethical reasons, but also due to increasing demand and regulatory pressure.
Key Developments:
- Increased Demand for Green Investments: There is growing client interest in green bonds, renewable energy investments, and companies that have sustainable practices.
- Regulatory Changes: Governments worldwide are introducing stricter ESG reporting standards, pushing wealth managers to prioritize sustainable investing strategies.
- Risk Management: ESG factors are now seen as essential in mitigating long-term investment risks, making them a core part of portfolio management.
4. Client-Centric Technology and Communication
In 2024, the focus will shift toward client-centric technology that enhances communication between wealth managers and their clients. The demand for transparency, real-time updates, and digital engagement is rising, especially among younger investors.
Key Developments:
- Client Portals: User-friendly client portals offering real-time updates, performance tracking, and reporting are becoming a must-have for wealth managers.
- Mobile Apps: More wealth management firms are offering apps that allow clients to track investments, receive advice, and engage with advisors remotely.
- Virtual Meetings and Consultations: Advisors are increasingly using video conferencing platforms to offer consultations, breaking down geographical barriers and providing more flexibility.
5. Focus on Intergenerational Wealth Transfer
As Baby Boomers continue to retire, wealth transfer to younger generations is accelerating. This trend is reshaping how wealth managers plan and structure their services, with a focus on preparing younger generations for wealth management.
Key Developments:
- Family Offices: The rise of family offices, which offer dedicated wealth management services to wealthy families, is helping families manage intergenerational wealth more effectively.
- Education and Mentorship Programs: Wealth managers are incorporating financial education and mentorship programs to help younger generations make informed investment decisions.
- Estate Planning Tools: Advanced estate planning tools and services that ensure smooth and tax-efficient wealth transfer are becoming a crucial part of wealth management offerings.
6. Increased Demand for Alternative Investments
In 2024, there is a growing interest in alternative investments as clients seek to diversify their portfolios beyond traditional stocks and bonds. Private equity, hedge funds, real estate, and cryptocurrency are gaining prominence among high-net-worth individuals (HNWIs) and institutional investors.
Key Developments:
- Cryptocurrency and Blockchain: Digital assets like Bitcoin and Ethereum, once considered fringe, are now seen as viable parts of a diversified investment strategy.
- Private Equity and Hedge Funds: Wealthy clients are looking beyond public markets, investing more heavily in private equity and hedge funds for potentially higher returns.
- Real Estate Investment Trusts (REITs): REITs are becoming increasingly popular as clients seek tangible assets that can provide stable returns and act as a hedge against inflation.
7. Holistic Financial Wellness
Wealth management is increasingly focusing on holistic financial wellness rather than just investment returns. Clients want to ensure that their entire financial situation—including debt management, tax efficiency, and retirement planning—is considered in their wealth strategy.
Key Developments:
- Comprehensive Financial Planning: Wealth managers are broadening their scope to include tax optimization, debt management, insurance, and long-term care in their advisory services.
- Wellness Programs: Some firms are launching financial wellness programs that help clients with budgeting, debt reduction, and overall financial well-being.
- Health and Wealth Correlation: There is a growing recognition of the link between financial security and overall well-being, with wealth managers providing advice that promotes both.
8. Regulatory and Compliance Changes
The wealth management industry is subject to increasing regulatory scrutiny, with 2024 bringing further regulatory changes aimed at protecting clients and promoting transparency.
Key Developments:
- Fiduciary Duty Expansion: Wealth managers are being held to higher fiduciary standards, meaning they must act in their clients’ best interests.
- Increased Reporting Requirements: Regulatory bodies are imposing stricter reporting standards, particularly around ESG and alternative investments.
- Cybersecurity: As wealth management becomes more digital, firms are investing heavily in cybersecurity to protect client data and prevent breaches.
Comparative Analysis of Wealth Management Trends in 2024
| Trend | Description | Key Focus Areas | Impact on Clients |
|---|---|---|---|
| Digital Transformation & Automation | Use of AI and technology to streamline services. | Robo-advisors, AI, automation | Faster, more cost-effective advice, personalized services |
| Personalization of Services | Tailoring financial advice to individual client needs and goals. | Behavioral finance, ESG investing | Customized financial strategies, better alignment with values |
| ESG and Sustainable Investing | Integrating environmental and social responsibility into investment portfolios. | Green investments, regulatory changes | Aligns investments with client values, mitigates long-term risks |
| Client-Centric Technology | Enhancing digital communication and transparency with clients. | Client portals, mobile apps | Improved accessibility to real-time updates and portfolio tracking |
| Intergenerational Wealth Transfer | Preparing younger generations to manage inherited wealth. | Family offices, education programs | Smooth transition of wealth, better preparedness for future financial responsibilities |
| Alternative Investments | Expanding beyond traditional investments into assets like crypto and private equity. | Cryptocurrency, private equity | Diversification of portfolios, potential for higher returns |
| Holistic Financial Wellness | Providing comprehensive financial advice that covers all aspects of financial health. | Tax planning, debt management | More comprehensive approach to managing personal finances |
| Regulatory and Compliance Changes | Adjustments to meet stricter regulations, especially around fiduciary duties and reporting. | Fiduciary duty, cybersecurity | Increased protection, transparency, and trust in services |
Analysis of the Key Wealth Management Trends in 2024
| Trend | Impact on Clients | Impact on Wealth Managers | Long-Term Outlook |
|---|---|---|---|
| Digital Transformation & Automation | Increased access to affordable services | Need to invest in AI and automation | Continued growth in technology-driven services |
| Personalization of Services | Better, more tailored financial advice | More client engagement and data use | Personalization will become standard practice |
| ESG and Sustainable Investing | Aligns values with investments | Requires expertise in sustainable finance | ESG will be a fundamental part of investment strategy |
| Client-Centric Technology | Easier access to portfolio information | Development of user-friendly platforms | Demand for seamless digital experiences will rise |
| Intergenerational Wealth Transfer | Younger generations are more informed | Need for education and mentorship | Will drive new wealth management strategies |
| Alternative Investments | Portfolio diversification | Advisors must stay informed of alternatives | Alternatives will become a regular portfolio feature |
| Holistic Financial Wellness | Improved overall financial health | Requires broader financial expertise | Holistic planning will be essential for long-term success |
| Regulatory and Compliance Changes | More transparency and protection | Need to adhere to stricter regulations | Regulatory burden will increase, requiring adaptation |
Conclusion
The wealth management landscape in 2024 will be shaped by technological advancements, personalized services, sustainable investing, and holistic financial wellness. Wealth managers who adapt to these trends will be well-positioned to meet the evolving needs of their clients, while those who resist change may struggle to stay relevant. As clients increasingly demand more transparency, customization, and ethical investments, wealth managers must be prepared to offer more than just investment advice—they must provide comprehensive financial solutions that help clients achieve both their financial and life goals.
Author


Buying a home ranks among the biggest financial decisions you will make. Therefore, finding a best cashback mortgage that suits your budget can make a significant difference to your finances. A cashback mortgage can provide an upfront payment after your mortgage completes. You can then use that money to manage some of the costs that come with moving into a new home.
However, you should not choose a mortgage simply because it offers a large cashback amount. The interest rate, product fees, repayment terms, and early repayment charges can have a much bigger effect on the total cost.
Whether you are buying your first home, moving to a new property, or considering a remortgage, a careful comparison can help you make a better decision. Speaking with a qualified mortgage adviser can also help you understand which options suit your financial situation.
What Is a Cashback Mortgage?
A cashback mortgage provides the borrower with a lump-sum payment after completing the mortgage. The lender usually pays the cashback shortly after completion, although the exact timing and conditions can vary.
You can use the money for several home-related expenses. For example, it may help with moving costs, solicitor fees, furniture, decorating, or other expenses that arise after buying a property.
Many UK lenders use cashback as an incentive to attract borrowers. However, each lender can offer different amounts and conditions. Some may combine cashback with competitive interest rates, while others may offer a larger incentive alongside higher borrowing costs. Therefore, always look at the complete mortgage package before making a decision.
Why Cashback Mortgages Appeal to UK Buyers
Buying a property involves more expenses than the deposit and mortgage payment. Buyers may also need to pay for legal services, surveys, removals, insurance, furniture, and other moving costs.
Cashback can provide some additional money during this expensive period. It may reduce the pressure on your savings and give you more flexibility after completion. For example, you could use the cashback toward:
- Solicitor and legal expenses
- Removal and moving costs
- Furniture and household items
- Decorating or minor improvements
- Other immediate home-buying expenses
However, cashback should remain only one part of your decision. A mortgage with a smaller cash incentive could still provide better value if it has a lower interest rate and fewer fees.
How to Compare Cashback Mortgage Offers
Comparing mortgages requires more than checking which lender offers the biggest cash payment. Instead, consider the total cost of the mortgage over the initial deal period. Start with the interest rate. Even a small difference in the rate can affect your monthly repayments and the amount of interest you pay.
Next, review the product or arrangement fee. Some lenders charge a significant upfront fee, which can reduce the benefit of the cashback. You should also check whether the mortgage has a fixed or variable rate. A fixed rate can provide predictable monthly payments for a specific period. A variable rate may change over time, which can affect your monthly budget.
Early repayment charges also deserve attention. These charges can limit your flexibility if you want to repay the mortgage early, move home, or switch products. When comparing the Best Cashback options, consider the entire financial package rather than focusing on the cash incentive alone.

Look at the Overall Mortgage Cost
A larger cashback payment does not automatically mean a better mortgage. For example, one lender may offer £1,500 cashback with a higher interest rate, while another may provide £500 cashback with a lower rate and fewer fees.
The second option could save you more money over the initial mortgage period. Therefore, calculate your expected payments and compare the total cost of each option. Consider the interest, fees, cashback, and any other charges that apply. This approach can give you a clearer picture of the actual value of each mortgage.
Choosing the Right Mortgage Lender
Different mortgage lenders have different eligibility requirements and product features. Some focus on competitive rates, while others attract customers through cashback or additional incentives.
When comparing lenders, consider their interest rates, affordability criteria, repayment flexibility, customer service, and account management options.
You should also check whether the lender offers cashback alongside other benefits. Some deals may include free valuations or contributions toward legal costs.
The Best Cashback mortgage does not necessarily come from the lender offering the largest payment. Instead, look for a lender that combines a suitable rate, reasonable fees, useful features, and a cashback incentive that genuinely benefits your situation.
Preparing for a Mortgage Application
Good financial preparation can improve your chances of finding a competitive mortgage. Before applying, review your credit report and check for inaccurate information. If you find an error, take steps to correct it before submitting an application. You can also reduce unnecessary debts where possible. A lower level of outstanding debt may improve your affordability position.
Avoid making several credit applications within a short period. Multiple applications can affect your credit profile and may make your finances look less stable to potential lenders.
It also helps to prepare your documents in advance. Lenders may request proof of income, identification, bank statements, and other financial information. If you feel uncertain about the process, an independent mortgage adviser can help you understand your options.
Can Existing Homeowners Benefit?
Cashback mortgages can also appeal to existing homeowners. If you are considering a remortgage, some lenders offer cashback as part of selected remortgage products.
This money may help cover some of the costs involved in switching lenders. Depending on the product, it could contribute toward legal fees, valuation expenses, or other costs.
However, you should still compare the total savings. A cashback remortgage may look attractive initially but could cost more if the interest rate or fees are significantly higher. Therefore, compare the new mortgage with your current deal and consider the complete cost before switching.
Common Mistakes to Avoid
Buyers can easily focus on the cashback figure and overlook other important details. Avoid making that mistake. First, check the arrangement or product fee. A high fee can reduce the value of the cashback. Next, compare interest rates carefully. A higher rate can increase your overall borrowing cost even when the cashback looks attractive.
You should also check early repayment charges and other conditions. Read the mortgage documents carefully so you understand your responsibilities. Finally, compare several mortgage options instead of choosing the first attractive offer. A broader comparison can help you identify better value.
How to Make a Smarter Mortgage Decision
Start by deciding what you can comfortably afford each month. Do not stretch your budget simply to qualify for a larger property or a bigger cashback incentive.
Next, compare the total mortgage cost across the initial deal period. Look at the interest rate, fees, cashback, and other charges together.
Also, think about your future plans. If you expect to move home or refinance within a few years, check whether early repayment charges could affect your plans.
For buyers who want Best Cashback offers, a balanced approach works best. The goal should not be to receive the largest payment. Instead, focus on finding a mortgage that supports your finances both now and over the longer term.
Final Thoughts
Finding the right cashback mortgage requires careful research. The cashback amount can help with upfront expenses, but it should never become the only reason you choose a particular deal.
Compare interest rates, fees, repayment conditions, lender flexibility, and the total cost of borrowing. Also, take time to prepare your finances before applying.
Whether you are buying your first property or exploring a remortgage, a thorough comparison can help you avoid unnecessary costs. With careful planning and professional guidance where needed, you can choose a mortgage that fits your budget and supports your future financial goals.
Author


Managing personal debt can become difficult when unexpected financial problems arise. A job loss, medical expense, reduced income, or sudden emergency can affect your ability to make regular loan payments. When these challenges continue, borrowers may start looking for alternatives to full repayment.
One option that may come up is Loan Settlement. It can reduce the amount you need to repay, but it can also affect your credit history and future borrowing options. Therefore, you should understand the process before making a decision.
A careful review of your finances can help you determine whether settlement makes sense. You can also use financial planning tools to understand your current obligations and prepare for future payments.
What Does Loan Settlement Mean?
Loan happens when a borrower and lender agree on an amount that is lower than the total outstanding loan balance. The borrower pays the agreed amount, usually as a lump sum, and the lender closes the account according to the settlement agreement.
People generally consider this option when they face serious financial difficulty and cannot repay the entire outstanding amount. However, lenders do not automatically accept every settlement request. They usually review the borrower’s situation before deciding whether to negotiate.
From the lender’s perspective, accepting a reduced payment may sometimes make more sense than continuing collection efforts when the borrower cannot afford the full amount.
For borrowers, settlement can reduce immediate financial pressure. However, it does not come without consequences. You should understand both the short-term relief and the possible long-term effects before proceeding.
How Does the Settlement Process Work?
Loan Settlement can reduce the immediate burden when full repayment becomes difficult. However, borrowers should carefully review the financial and credit-related consequences before choosing this option.
Review Your Financial Situation
Start by looking at your income, expenses, savings, debts, and available cash. Determine whether you can realistically make regular payments or arrange a lump-sum amount. A personal loan EMI calculator can help you understand your current monthly obligations. It can also show how your loan amount, interest rate, and repayment period affect your monthly payment.
Contact Your Lender
Once you understand your financial position, contact the lender. Explain your circumstances clearly and honestly. If you experienced a significant change in income or unexpected expenses, provide relevant information when requested. Open communication can help the lender understand why you cannot continue with the original repayment schedule.
Discuss the Settlement Amount
If the lender agrees to discuss settlement, you can negotiate the amount and terms. Do not rely only on verbal promises. Ask the lender to provide the complete agreement in writing.
Review the settlement amount, payment deadline, account status, and any information related to your credit report before making a payment.
Make the Agreed Payment
After both sides finalize the agreement, make the payment within the specified period. Keep proof of payment and copies of all related documents. Missing the agreed deadline could create additional complications, so make sure you understand the payment conditions.
Obtain Written Confirmation
After making the payment, request written confirmation from the lender. Keep this document with your financial records. It can help you prove that you completed the agreed arrangement if questions arise later.
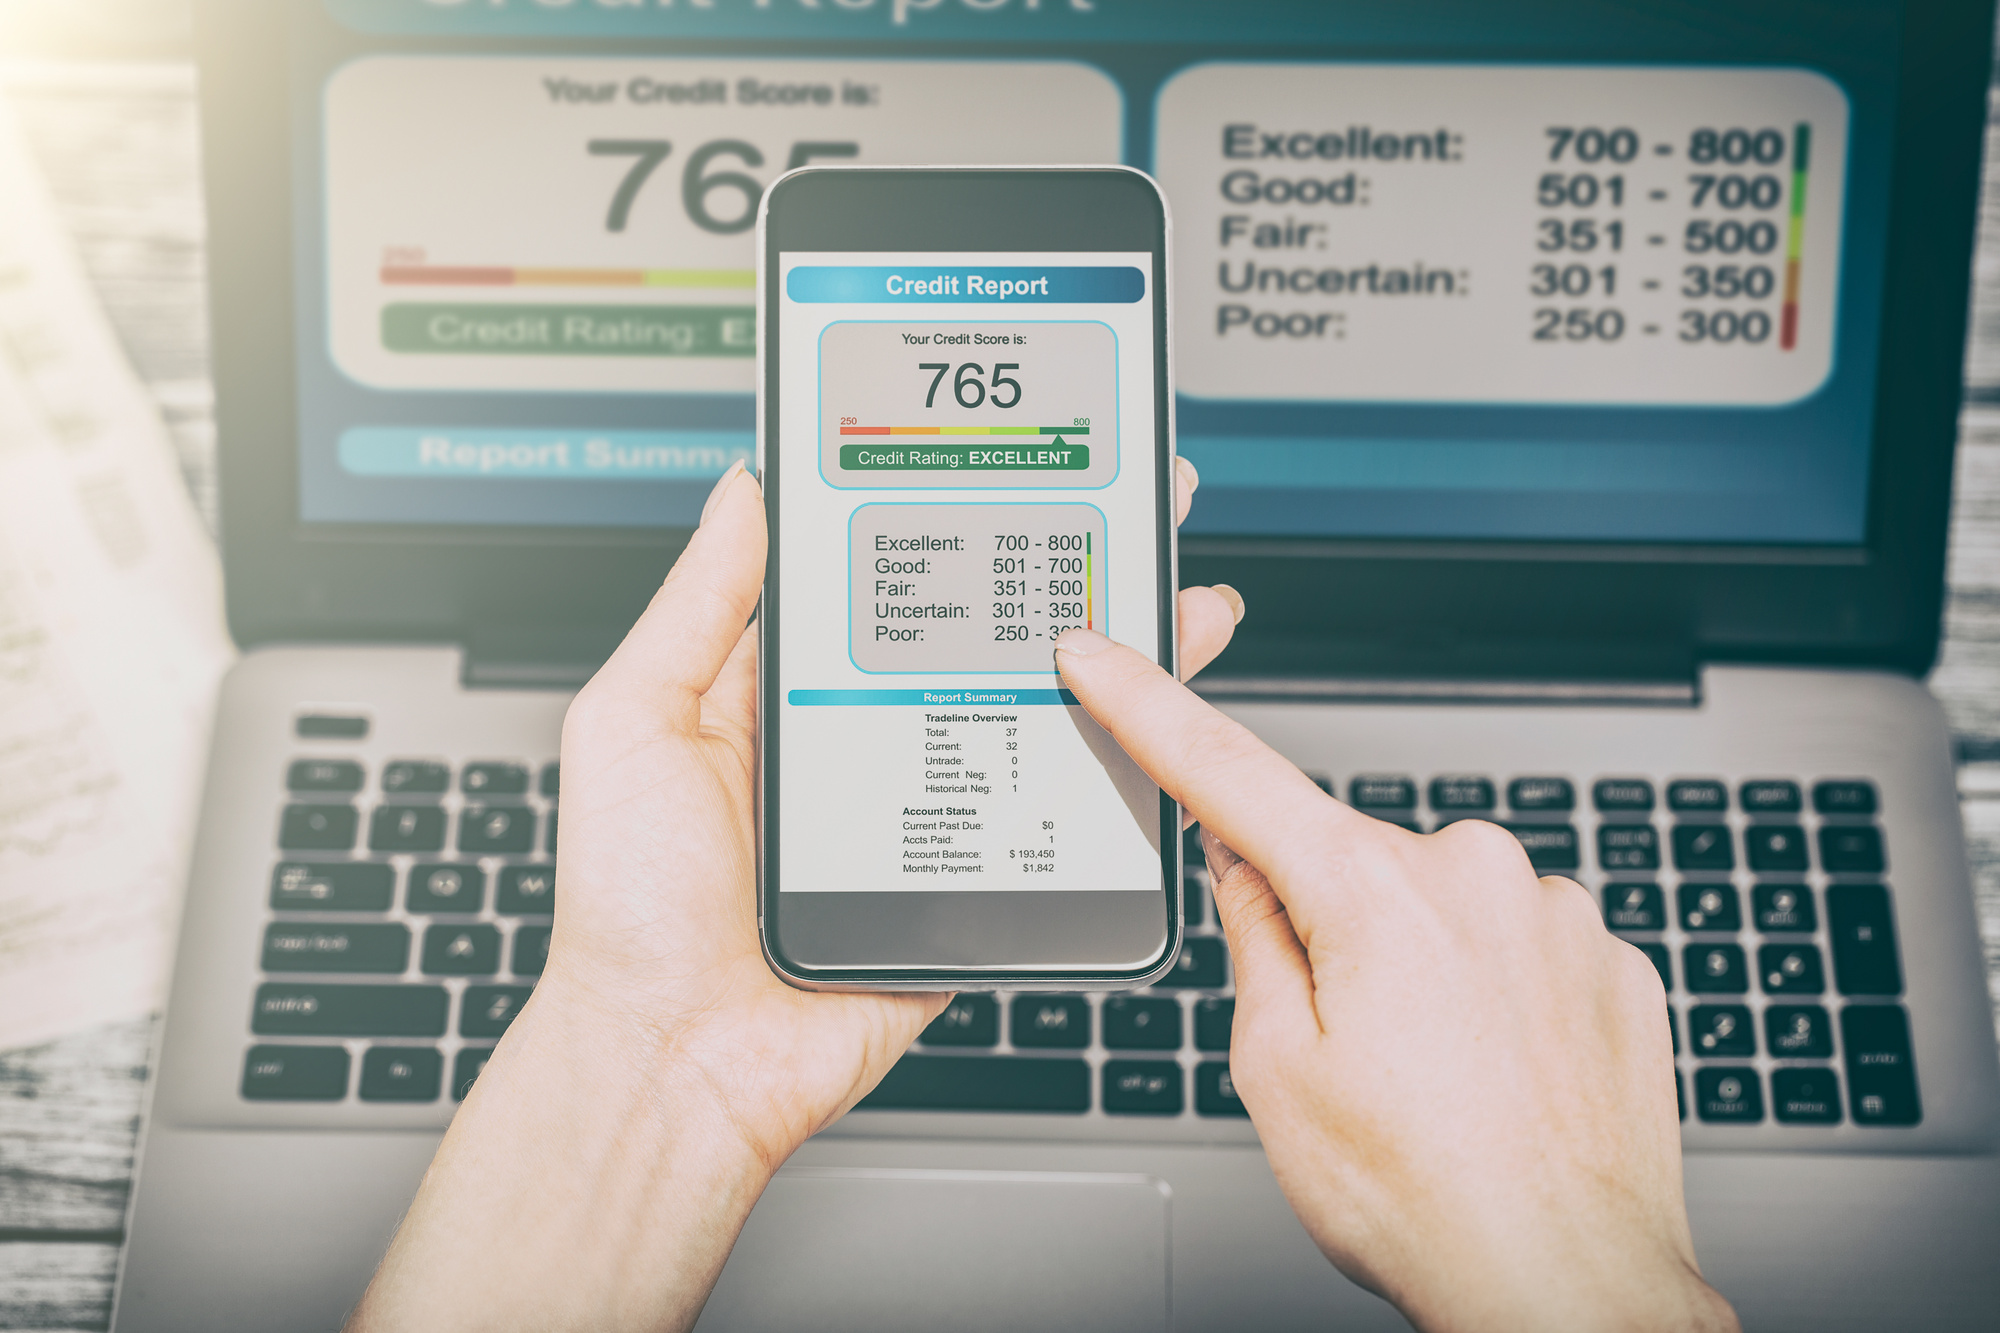
How Can Settlement Affect Your Credit Score?
Loan Settlement can provide immediate relief, but it may negatively affect your credit profile. A lender may report the account as settled rather than fully paid.
This distinction matters because future lenders can see that you paid less than the original amount owed. As a result, they may consider you a higher-risk borrower.
Credit Report Impact
A settled account can appear differently from an account that you paid in full. Lenders reviewing your credit history may take this information into account when evaluating future applications.
Possible Credit Score Reduction
Your credit score may fall after settlement. The impact depends on your overall credit history, payment behavior, existing accounts, and other factors.
The effect can vary from one borrower to another. Therefore, you should not assume that every settlement will produce the same result.
Future Borrowing Challenges
After settlement, obtaining a new loan or credit card may become more difficult. Some lenders may offer credit only at higher interest rates or with stricter conditions. For this reason, borrowers should consider their future financial needs before choosing this route.
Steps to Rebuild Your Credit
A settlement does not mean that you cannot improve your credit profile. You can take several practical steps after resolving the account. First, make every future loan and credit payment on time. Consistent payment behavior can help demonstrate better financial management.
Next, keep your credit utilization under control. Using a smaller portion of your available credit can support healthier credit management.
You should also review your credit report regularly. Check for inaccurate information and monitor changes in your credit profile. If you find an error, contact the appropriate credit reporting agency or lender. Most importantly, avoid taking on unnecessary debt while rebuilding your financial position.
How a Personal Loan EMI Calculator Can Help
Financial planning becomes especially important when you face repayment difficulties. A personal loan EMI calculator can help you understand how much you currently pay each month.
To use one, enter details such as the loan principal, interest rate, and repayment tenure. The calculator can then estimate your monthly EMI.
This information can help you review your budget. You can compare your monthly loan payment with your income and regular expenses.
You can also experiment with different loan amounts and repayment periods. This can help you understand how changing the loan structure may affect your monthly obligations.
However, an EMI calculator only provides an estimate. It cannot determine whether a lender will accept a settlement request or predict the exact impact on your credit score.
Consider Your Long-Term Financial Health
Before choosing settlement, consider all available options. Depending on your situation, you may be able to negotiate a revised repayment schedule, request temporary relief, refinance the debt, or adjust your monthly budget.
Each option has different advantages and risks. Therefore, avoid making a quick decision based only on immediate financial pressure.
If you have enough savings to make a settlement payment, think carefully about how that payment will affect your emergency fund. Using all your available cash may leave you vulnerable to another unexpected expense.
You should also understand the terms provided by your lender. If the financial situation feels complicated, consider speaking with a qualified financial professional before making a decision.
Final Thoughts
Loan Settlement can provide relief when financial difficulties make regular repayments unrealistic. However, borrowers should consider the wider consequences before accepting an agreement.
Understand your finances, communicate clearly with your lender, review every term in writing, and keep proof of all payments. At the same time, use tools such as a personal loan EMI calculator to understand your monthly obligations and plan your finances more effectively.
After resolving the debt, focus on rebuilding healthy financial habits. Make payments on time, manage credit carefully, and monitor your credit report.
Most importantly, look beyond the immediate relief. A decision that helps today should also support your financial stability in the years ahead.
Author


Buying a truck for business use can feel like a major commercial truck financial step. Whether you need your first vehicle, want to replace an aging truck, or plan to expand your fleet, the right financing can make the purchase easier to manage.
However, choosing a financing option requires more than checking the monthly payment. The purchase price, truck condition, down payment, loan term, credit profile, and business finances can all affect your final terms.
A smart approach starts with understanding how financing works. Then, you can compare your options and choose a payment structure that supports your business instead of putting unnecessary pressure on your cash flow.
What Is Truck Financing?
Tuck financing allows businesses and owner-operators to purchase a truck without paying the entire cost upfront. Instead, you finance part of the purchase and repay the amount over a set period.
Depending on the financing program and the lender, you may find options for semi-trucks, tractor-trailers, day cabs, box trucks, dump trucks, tow trucks, reefer trucks, work trucks, and fleet vehicles.
You can also find financing for both new and used equipment. However, the right option depends on your business needs, financial situation, and the truck you plan to purchase.
Before moving forward, consider how the vehicle will contribute to your operation. A truck should support your business goals while keeping your overall expenses manageable.
How Do Commercial Truck Loans Work?
Truck loans help businesses spread the cost of a truck over an agreed repayment period. The amount you can finance often depends on several factors. These may include the truck’s purchase price, value, age, condition, your down payment, financial history, and lender requirements.
Instead of paying the full amount at the time of purchase, you make regular payments according to the financing agreement. Still, don’t focus only on the monthly payment. A longer repayment period may reduce your monthly expense, but it can increase the total interest you pay overtime.
Therefore, review the complete financing structure before signing an agreement. Compare the interest rate, repayment period, fees, down payment, and total repayment amount.
What Can Affect Your Approval?
Every lender has its own requirements. However, many lenders review both personal and business information when evaluating an application.
Your credit history can matter, but it isn’t the only consideration. Lenders may also review your time in business, revenue, cash flow, existing financial obligations, down payment, and the truck’s age and condition.
Your application should tell a clear story. Explain what you want to purchase, how you plan to use it, and how the truck will support your business.
Strong and accurate documentation can also make the process smoother. Before applying, organize your financial information and purchase details so you can respond quickly to lender requests.
How Much Should You Put Down?
There isn’t one down payment amount that works for every buyer. Your required amount can depend on the truck, financing program, credit profile, business history, and other factors.
A larger down payment reduces the amount you need to finance. However, putting too much cash into the purchase can leave your business with less money for everyday expenses.
For example, you may need cash for fuel, insurance, maintenance, payroll, or unexpected repairs. As a result, think about your working capital before deciding how much to put down.
The goal isn’t simply to make the largest possible down payment. Instead, choose an amount that balances the purchase with your ongoing business needs.
Can You Get Financing with Bad Credit?
Less-than-perfect credit does not always prevent you from obtaining financing. Some financing programs consider applicants with credit challenges. However, the available terms can vary significantly.
Lenders may look at your complete financial picture rather than focusing on your credit score alone. Business revenue, time in operation, existing obligations, down payment, and the truck itself can all influence the decision.
If your credit history has some issues, provide accurate information and discuss your situation with a financing professional. Most importantly, don’t accept financing simply because you qualify. Make sure the payment and total cost work for your business in the long run.
Financing a New Truck
A new truck can offer several advantages. New equipment often comes with updated technology, modern safety features, and fewer immediate maintenance concerns. It may also provide a longer expected service life.
However, new trucks generally cost more than used equipment. That higher purchase price can increase your monthly payment and overall financing cost.
Before buying new, calculate the complete cost of ownership. Include the loan payment, insurance, fuel, maintenance, registration, and other operating expenses. Then consider whether the truck’s benefits justify the additional cost.
Financing a Used Commercial Truck
Used trucks can provide a more affordable entry point for businesses that want to control their initial investment. However, buyers should pay close attention to the vehicle’s age, mileage, condition, and maintenance history.
Before purchasing a used truck, arrange a professional inspection. Also, review available service records and look for signs of major mechanical problems.
A lower purchase price doesn’t always mean lower ownership costs. A truck that needs frequent repairs can quickly become expensive. Therefore, consider both the purchase price and the truck’s expected operating costs.
What Documents Do You Need?
Financing requirements vary between lenders. Still, buyers should generally prepare basic business and financial information before starting the application. You may need business details, identification, purchase information, financial records, and information about existing obligations. Accurate documentation can help prevent unnecessary delays. It also gives the lender a clearer picture of your financial position.
If you’re a first-time buyer, don’t assume that you cannot qualify. Lenders may consider your credit, income, experience, down payment, and the truck together. It also helps to establish a realistic budget before visiting dealerships or browsing trucks. Knowing your budget can keep you focused on equipment that fits your business.
Why Get Financing Before Shopping?
Getting to finance arranged before shopping can give you a clearer idea of what you can afford. You can establish a realistic budget and focus on trucks that match it. Furthermore, having financing prepared may help you move faster when you find the right vehicle. You can approach the purchase with a better understanding of your financial limits.
Choosing the Right Financing Company
Choosing a lender deserves the same attention as choosing the truck. Look for a company that understands business vehicles and offers financing for the type of equipment you need. Ask questions about rates, repayment terms, fees, down payments, and eligibility. Don’t choose a lender based only on an advertised interest rate.
Instead, compare the complete financing package. Clear communication and straightforward terms can make the borrowing experience much easier.
Finance Your Next Truck With Lewis Capital
The right truck can support business growth, but the right financing can help you protect your cash flow while making that investment. Lewis Capital offers Commercial Truck financing for businesses and owner-operators purchasing new or used trucks. Whether you’re buying your first truck, replacing an older vehicle, or expanding your fleet, explore financing options that align with your business goals and budget.
Final Thoughts
Buying a truck can play an important role in your business growth. However, the financing decision deserves careful attention. Look beyond the monthly payment and consider the full cost of ownership, including interest, insurance, fuel, maintenance, and other expenses.
Take time to compare lenders, understand the repayment terms, and choose a truck that fits your actual business needs. Also, keep enough working capital available for everyday operations and unexpected costs.
Whether you need a new or used Commercial Truck, the right financing can make the purchase more manageable. With proper planning and a clear understanding of your options, you can move forward with greater confidence and protect your business’s financial health.
Author


Cylinder Volume: The Complete Guide to Calculating Volume Accurately

Best Bourbon Tours in Kentucky: Choosing the Right Tour for You

Cabinet Shop Drawings for Precise Fabrication and Installation

Auto Repair Digital Marketing: Grow Your Automotive Business Online

Residential Drafting Services for Remodeling and Renovation Plans

Raised Bed Soil Calculator: How Much Soil Do You Really Need?

3 Best Rhude Hoodies for UK Style 2026

Revit Drafting Solutions for Accurate BIM Projects

How to Find Mobile App Developers in Dubai for Android & iOS Apps

How Do IDA Jacket Designs Balance Function, Comfort, and Style?

Cybersecurity Consulting Company SequelNet Provides Critical IT Support Services to Medical Billing Firm, Medical Optimum

Meet the Megalodon: The Shark Star of ‘Meg 2’

Reduce Video Game Lag: Level Up Your Gaming Performance
Balancing India’s Entertainment: Cricket vs. Bollywood

Jetsetter’s Secrets: Unveiling Our Favorite Travel Hacks for a Seamless Adventure

The 5 Best Live Sports Streaming Sites: Legal and Exciting!

Hollywood Labor Unrest: The Impact of ‘What About Us?’ Strikes

Unveiling the Magic of Dream Fulfillment at the Late NBA Draft

Illuminate Your Skin: Dr. Axe Unveils Natural Remedies for Lightening Knees and Elbows

Bright Choices: Navigating the Pros and Cons of Skin Whitening Creams with Dr. Axe
-

 Business3 years ago
Cybersecurity Consulting Company SequelNet Provides Critical IT Support Services to Medical Billing Firm, Medical Optimum
-
Entertainment3 years ago
Meet the Megalodon: The Shark Star of ‘Meg 2’
-
Entertainment3 years ago
Reduce Video Game Lag: Level Up Your Gaming Performance
-
 Sports3 years ago
Balancing India’s Entertainment: Cricket vs. Bollywood
-
Entertainment3 years ago
Jetsetter’s Secrets: Unveiling Our Favorite Travel Hacks for a Seamless Adventure
-
Productivity3 years ago
The 5 Best Live Sports Streaming Sites: Legal and Exciting!
-
Art /Entertainment3 years ago
Hollywood Labor Unrest: The Impact of ‘What About Us?’ Strikes
-
Sports3 years ago
Unveiling the Magic of Dream Fulfillment at the Late NBA Draft